Sasin Research Seminar - A Planner-Trader Decomposition for Multi-Market Hydro Scheduling
05 November 2026
You are cordially invited to join Sasin Research Seminar.
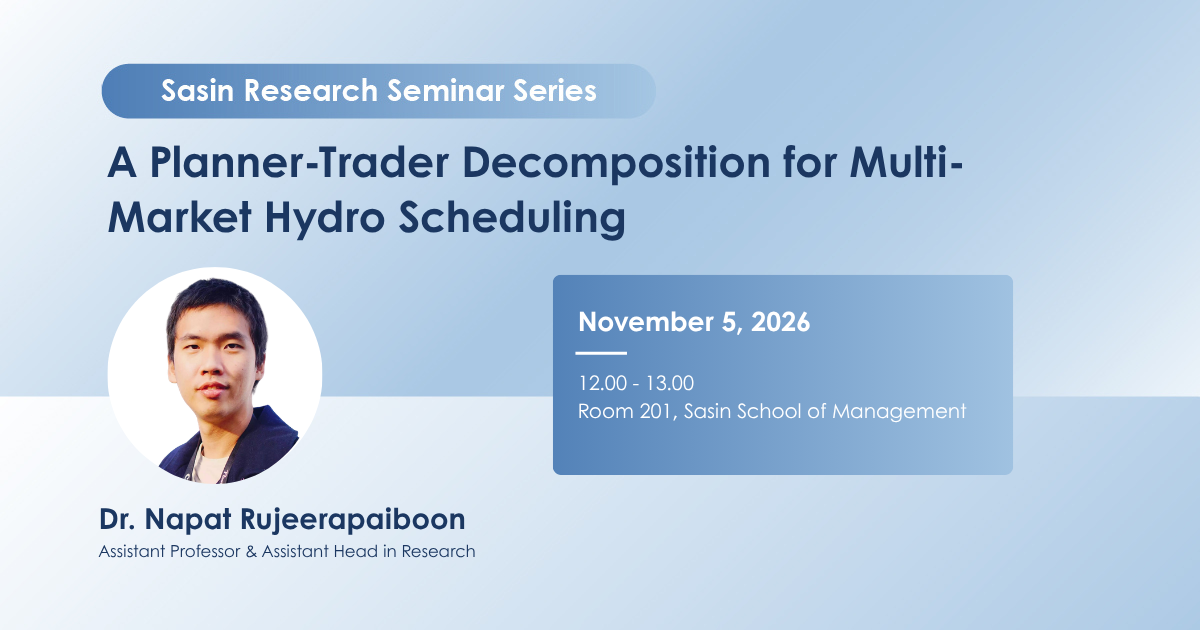
A Planner-Trader Decomposition for Multi-Market Hydro Scheduling
By: Dr. Napat Rujeerapaiboon Assistant Professor & Assistant Head in Research This research presents a new stochastic optimization framework for hydropower trading that integrates participation in both spot and reserve markets. Using a planner-trader approach, the study addresses market uncertainty and declining peak/off-peak price spreads, which are reducing hydropower arbitrage opportunities. Numerical experiments using an Austrian hydropower cascade demonstrate the effectiveness of the proposed framework. Date: Friday, November 5, 2026 Time: 12.00-13.00 (Bangkok Time) Venue: Room 201 at Sasin School of Management or online via Zoom Register here to reserve your seat Abstract: Peak/off-peak spreads in European electricity markets are eroding due to the ongoing nuclear phaseout and growing photovoltaic capacity, reducing hydropower arbitrage profits and increasing the importance of reserve markets. We propose a bi-layer planner-trader stochastic programming framework for operating interconnected hydropower plants in spot and reserve markets. The planner sets end-of-day reservoir targets, while the trader chooses hourly market bids. Under a one-day-ahead information restriction, the trader’s infinite-dimensional 25-stage problem reduces to a finite two-stage stochastic program with two scenarios. Approximating reservoir targets by affine decision rules then reduces the planner’s infinite-dimensional 365-stage problem to a tractable two-stage program solvable by sample average approximation. Numerical experiments on an Austrian hydropower cascade demonstrate the framework’s effectiveness. For more information please contact +66-2218-4000 ext. 84095 or [email protected].Share this article